


Mortgage rates have spent most of October above 7%, the highest they have been in almost three years. If you are thinking about buying a home in Garden City, Holcomb or anywhere in Finney County, that number changes the math. Here is what higher rates actually do to your budget, and what you can do about it.
Where Rates Stand Right Now
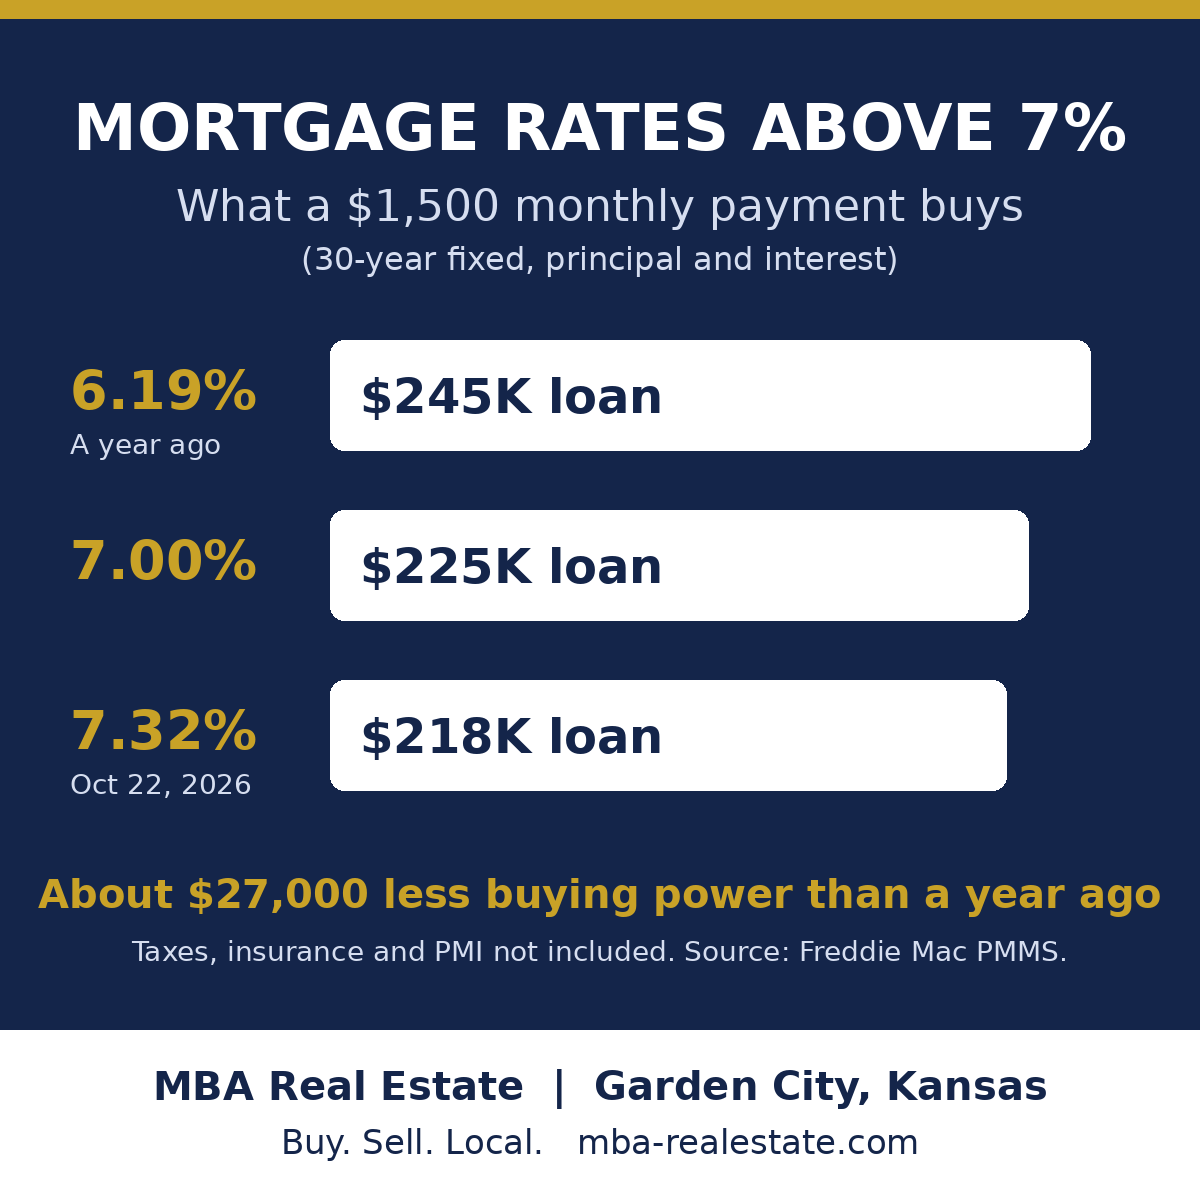
Freddie Mac's average 30-year fixed rate was 7.32% for the week of October 22, 2026, down from 7.40% the two weeks before. That was the first weekly decline since August, after seven straight weekly increases pushed rates to their highest level since November 2023. A year ago, the same average was 6.19% (Freddie Mac). Freddie Mac publishes a new weekly reading every Thursday, and we track it in our weekly market reports.
What a Higher Rate Does to Your Payment
On a $200,000 loan, here is the monthly principal and interest on a 30-year fixed mortgage at different rates:
- 6.19% (a year ago): about $1,224 a month
- 6.50%: about $1,264 a month
- 7.00%: about $1,331 a month
- 7.32% (current average): about $1,374 a month
That is roughly $150 more every month for the same loan, or about $1,800 a year. Property taxes, homeowners insurance and any mortgage insurance come on top of these numbers.
The Flip Side: How Much House Your Budget Buys
Most buyers start with a monthly payment they are comfortable with, not a loan amount. Say that number is $1,500 a month for principal and interest. At 6.19%, that payment supported a loan of about $245,000. At 7.32%, the same $1,500 supports about $218,000. That is roughly $27,000 less buying power, without your income or savings changing at all.
In a market where Finney County's weekly median sales price has recently ranged from about $165,000 to $351,000, $27,000 can be the difference between two very different homes, or between two neighborhoods.
Six Ways to Stretch Your Buying Power
- Get pre-approved before you shop. A pre-approval tells you exactly what you qualify for at today's rates, so you are not falling in love with homes outside your budget. It also makes your offer stronger.
- Compare more than one lender. Rates and fees vary from lender to lender, and on any given day the gap between them can be bigger than a week's move in the national average. Even a quarter point makes a difference over 30 years.
- Look at assistance programs. The Kansas Housing Resources Corporation's First Time Homebuyer Program offers an interest-free loan of 15 or 20 percent of the purchase price for income-eligible buyers, forgiven if you stay in the home for 10 years. It is also open to buyers who have not owned a home in at least three years (Kansas Housing Resources Corporation). Ask your lender whether you qualify.
- Ask about a rate buydown. Paying points, or negotiating for the seller to help with a temporary or permanent buydown, can lower your rate and payment. With price reductions picking up across Finney County this fall, some sellers are open to helping with closing costs instead of cutting price.
- Know your loan options. FHA, VA and USDA loans each have their own rates, down payment requirements and mortgage insurance rules. The right fit depends on your situation, so talk it through with a local lender.
- Think about the long game. If rates come down later, refinancing may be an option. Buying the right home at the right price today, at a payment you can live with, matters more than trying to time the market perfectly.
Is It Still a Good Time to Buy?
That depends on your plans, not the headlines. Higher rates have cooled competition, and buyers in Finney County have more room to negotiate than they did a couple of years ago. If you plan to stay put for several years and the payment fits your budget, waiting for lower rates can mean competing with more buyers when they do come down. If the numbers do not work yet, a good lender can help you build a plan to get there.
Talk With a Local Agent
MBA Real Estate can show you any home on the market, not just our own listings. Browse Garden City homes for sale, schedule a showing, or contact MBA Real Estate. You can also call our office at 620-275-7440.
Payment examples are estimates of principal and interest only on a 30-year fixed loan and are for illustration. Your rate and payment will depend on your credit, down payment, loan type and lender. MBA Real Estate is not a lender; talk with a licensed loan officer for a personalized quote.
Buy. Sell. Local.